How You Can Create a Realistic Budget for Your Lifestyle?
Most budgets fail for the same reason. They are built for a perfect version of you who never orders a takeaway, never buys a round, and never has a bad week.
A realistic budget works differently. It starts with the life you actually live, then makes the numbers fit around it. Even money guide sites make the same point: a plan only helps if you can stick to it. Here is how to build one that lasts.
Start With What Actually Comes In
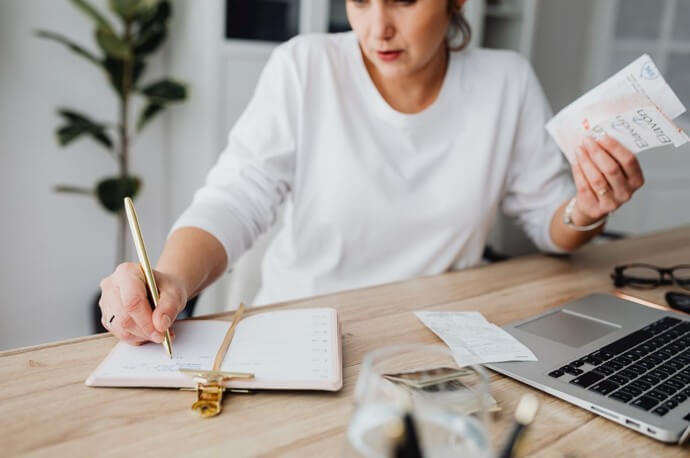
Start with your actual earnings, not what you get on the contract. Use amounts after tax, pension, and deductions at source.
If you have a fluctuating income, use the average of the last 6 months and plan on the minimum. Include any additional income received (including benefits and other side income). The maximum you can do for any other expense such as rent, bills, food, or any loans that you’re paying off.
Put Your Debt Repayments in First
Debt payments are not optional, so they belong near the top of the page rather than squeezed in at the end.
Write down the minimum payment on every credit card bill or short-term loans from direct lenders like Monixa, along with the interest rate. The minimums are fixed costs in the budget. It is then possible to use the money left over to cover the highest balance to pay it down as quickly as possible. Keep in mind that you’re only increasing your monthly payment if you have the funds available and can afford it, after you’ve paid your rent and bills.
List Your Fixed Costs Honestly
Then there are those bills you don’t choose to pay for: rent or mortgage, council tax, energy, water, broadband, mobile, insurance and travel to work.
Don’t use the previous year’s figures or an estimation. Use the actual amounts and the balance of the last 3 months of statements. Don’t forget annual expenses such as car tax or car insurance, which you can also calculate on a monthly basis by dividing it by 12. The problem that most budgets are broken with is a faulty guess.
Work Out What Your Lifestyle Really Costs
It is here that people cheat. For the next 3 months, practice tracking your spending and calculate what you actually spend on food, coffee, nights out, clothes, hobbies, and the children.
You might not like the sum, but it’s the truth, and a real budget is a budget that can be adhered to. If it is greater than you thought, then it is helpful information and not a failure. The pressure is in your hands now.
Choose a Method That Suits You
Budgeting is not a one-size-fits-all solution, but one that you’ll stick with.
50/30/20 means you put 50 percent of your income toward your needs, 30 percent toward your wants, and 20 percent toward your savings and debt. Others like to keep expenditures in different pots to be able to look at the amount of money available at one glance. Others just put a limit on how much they can spend per week and when that is reached, they stop spending. Use for 2 months and then change.
Leave Room for Fun and Mistakes
A budget with no enjoyment in it is a diet that ends in a biscuit binge. You need some money you are allowed to waste.
Do the same each month, set aside a specific amount for a specific thing, and don’t feel guilty about it. Include an extra £30/40 for the items you forget: School trip, birthday present, parking ticket. Budgets are unworkable because they are too tight, not because they are too high.
Build In Savings From the Start
If there is something left over at the end of the month, then it’s almost always a small amount. Treat this as a bill.
Set up a standing order for payday so the money moves before you can spend it. Start with an emergency pot of £500, then build towards three months of essential costs. Also save monthly for the big one-off bills you know are coming, like Christmas, car insurance and holidays. Even £20 a month counts.
Track It in a Way You Will Keep Up
The most elaborate system will be ineffective if you don’t use it for 2 weeks. Any notes application, any piece of paper, or a plain spreadsheet will suffice.
Check in once a week for 5 minutes; don’t be doing it all day. There are a lot of banking apps that do category classification automatically, which saves a lot of work. The aim is not perfect records. It’s the awareness that you have an approximate idea of where you stand before payday. Short, regular beats that are elaborated and dropped.
Review It Every Few Months
Within a few weeks, your budget will be incorrect, and that’s perfectly fine. Things change and so do prices.
Take a seat every three months and review how your plan worked out against how things actually went. Don’t make excuses that it will get better. If you keep going over money in one place, increase it and subtract from another area so you don’t have to be “overspending.” A budget is not a commitment but a work document. When adjusted, it is known that it is in use.
Final Words
A realistic budget is not a “no spending” budget. It’s all about planning ahead for how your money will be spent.
Begin with what you can afford, pay off your debts and fixed expenses, be realistic about your lifestyle, and budget for fun. Then monitor it periodically and modify as needed. If you do that, you’ll have an answer to the question: “Where do I stand?” Which is half the battle. This is sufficient to reduce the stress.
Frequently Asked Questions
How do I budget when my income changes?
Take the lowest month as your benchmark, and anything higher will be considered a bonus. Use the extra money to pay your regular bills, but not to increase the bills themselves, such as paying into savings or debt. Helps to maintain stability.
What if my outgoings are more than my income?
Cut the flexible costs first and then talk to your suppliers and lenders. Citizens Advice and StepChange both offer free support, and there are numerous people who are eligible for support. Do not wait.
How much should I budget for savings?
A common goal is to save about 20% of your pay, but get started by saving as much as you can. Every £25 is worth more than an audacious number that you drop soon. Raise it over time.
Why do my budgets keep failing?
Typically due to dogma or educated guesses. Take actual amounts from your statements, factor in spending money for fun, and be prepared to fine-tune as you go. We don’t aim for perfection.
Popular on OTW Right Now!
About The Author

Gagan Bhangu
Founder of otechworld.com and managing editor. He is a tech geek, web-developer, and blogger. He holds a master's degree in computer applications and making money online since 2015.